
 Market Data
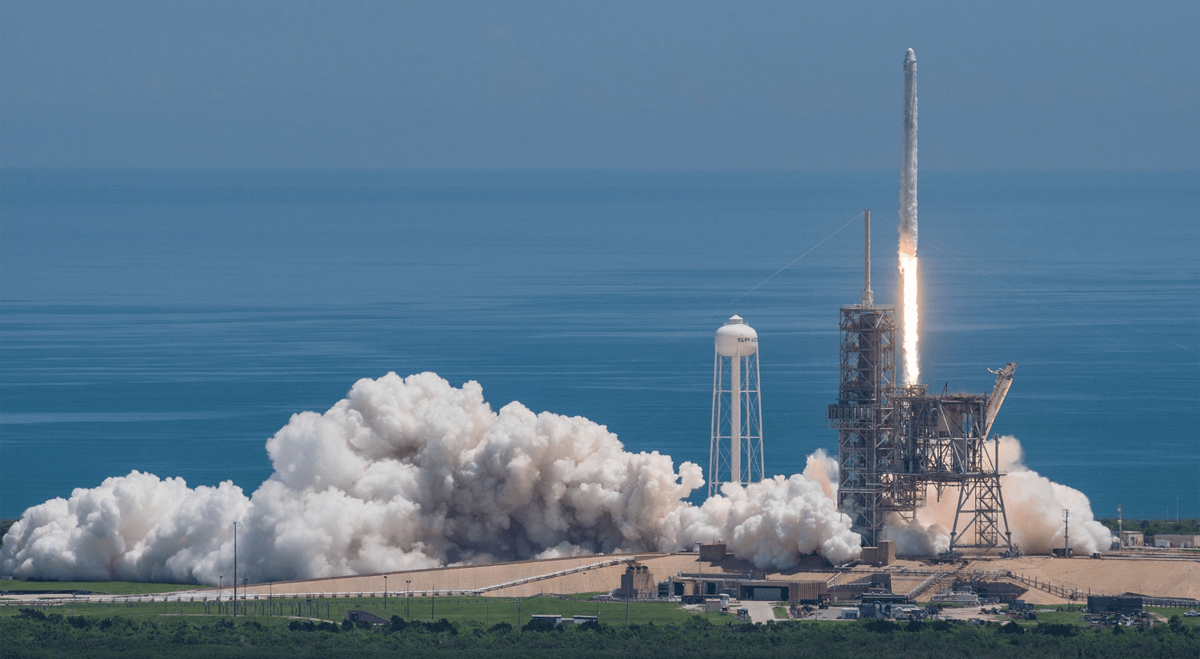
© Mil Pic
SpaceX (NASDAQ:SPCX) trades at a discount to other large-cap AI-related companies when its expected growth is taken into account, according to Morgan Stanley analyst Adam Jonas, who reiterated an Overweight rating and $300 price target on the stock.
Jonas described SpaceX as “cheap and getting cheaper” on a growth-adjusted basis, despite the shares trading at a higher headline valuation multiple than a group of mega-cap AI-related companies.
According to the analyst, SpaceX trades at approximately 30 times estimated 2028 enterprise value to EBIT, compared with around 16 times for other mega-cap AI enablers.
However, Jonas calculated that SpaceX trades at approximately 0.3 times 2028 EV/EBIT/Growth, around 40% below the 0.5 times median for the comparison group.
At Morgan Stanley’s $300 price target, Jonas estimates the ratio would increase to approximately 0.6 times, which he said would be in line with Amazon (NASDAQ:AMZN) and below Alphabet (NASDAQ:GOOGL) and Meta (NASDAQ:META).
Jonas said investor interest in SpaceX shares has recently been limited. Referring to a meeting with 40 clients last week, he said “not a single hand went up” when he asked who owned the stock, adding that “it’s been really, really quiet on SPCX lately.”
The analyst said concerns including Grok’s performance relative to other frontier AI models and spectrum availability for Starlink Mobile are reflected in the current valuation.
Jonas described valuing SpaceX as “more of an ’and’ problem than an ’or’ problem,” referring to the need to consider the company’s interconnected businesses together.
At a share price of $159, Jonas estimated that the market is assigning most or all of the $127-per-share value he attributes to SpaceX’s Space and Connectivity operations, leaving approximately $32 per share attributable to AI.
He said that implied valuation is equivalent to approximately three times estimated 2028 enterprise value to sales for a neocloud-type business.
According to Jonas, a decline in the shares to $100 within 12 months would require a clear slowdown in AI development, a significant setback in Starship testing or a material dilutive event.
Jonas identified compute pricing as an important variable in SpaceX’s valuation.
Consensus estimates assume pricing of $17.60 per watt across 4.1 gigawatts of capacity. On those assumptions, Jonas calculated that every additional $10 per watt would add more than $40 billion in revenue.
He said SpaceX’s recent short-term neocloud contracts have been priced at between $30 and $50 per watt.
The analyst identified several upcoming events that could affect investor expectations, including Starship Flight 15 in late October or early November. Jonas said a successful ship catch “could be the biggest positive catalyst since the IPO.”
Other events cited by Jonas include third-quarter earnings in late October, Starship Flight 16 before the end of the year, planned Grok 4.8, 4.9 and 5.0 releases and potential additional neocloud agreements.
Morgan Stanley identified risks including slower progress on Starship reusability, lower enterprise AI monetisation, higher compute costs per watt, longer time-to-power requirements, additional funding needs and regulatory delays.
Join the discussion: Connect with other investors on your favorite stocks or explore the top-talked-about stocks on our Breakout Boards.
This article was written by the editorial team at InvestorsHub/ADVFN and is provided for informational purposes only. In some cases, editorial staff may use artificial intelligence–based tools to assist in the research, drafting, or editing of content, under human review and oversight. This article does not constitute investment advice, a recommendation, or an offer to buy or sell any securities. The views expressed are based on publicly available information believed to be reliable at the time of publication, but accuracy or completeness is not guaranteed. Readers should conduct their own independent research and consult a qualified financial professional before making any investment decisions.


 mdb1
33 minutes ago
uksausage
42 minutes ago
mdb1
4 hours ago
 Curt D
5 hours ago
 Wayne R
9 hours ago
 zen222
21 hours ago
Curt D
23 hours ago
 iHub Time Traveler
23 hours ago
Curt D
1 day ago
iHub Time Traveler
1 day ago
Curt D
1 day ago
dcwisc
1 day ago
 Watts Watt
2 days ago
iHub Time Traveler
2 days ago
zen222
2 days ago
zen222
2 days ago
iHub Time Traveler
2 days ago
 iHub News
2 days ago
Watts Watt
3 days ago
zen222
3 days ago
zen222
3 days ago
zen222
3 days ago
zen222
3 days ago
Watts Watt
3 days ago
Watts Watt
3 days ago
 makinezmoney
3 days ago
makinezmoney
3 days ago
Curt D
3 days ago
 Nysegolfa
3 days ago
Watts Watt
3 days ago
mtsr
3 days ago
Watts Watt
3 days ago
ShawnP123
3 days ago
Thompson123
3 days ago
iHub News
3 days ago
Watts Watt
3 days ago
Watts Watt
3 days ago
Watts Watt
3 days ago
Watts Watt
3 days ago
zen222
4 days ago
 alchemytrader
4 days ago
alchemytrader
4 days ago
Watts Watt
4 days ago
BDEZ
4 days ago


It looks like you are not logged in. Click the button below to log in and keep track of your recent history.


 Customized watchlists with full streaming quotes from leading exchanges, such as NASDAQ, NYSE, AMEX, OTC Markets Small-Cap, LSE and more.






Morgan Stanley Reiterates $300 SpaceX Target, Citing Growth-Adjusted Valuation
SpaceX (NASDAQ:SPCX) trades at a discount to other large-cap AI-related...